
What does a mortgage broker actually do?
Find the best deal you can achieve, then fight your corner until you get the keys. Our adviser Paul Manns explains the job, and why it's worth calling a broker earlier than you think.
What a mortgage broker does, day to day.
We act as a go-between, especially for people whose circumstances make the high street harder.
Find the best deal you can achieve
Complex income, adverse credit from the past, plenty of things decide whether an application succeeds. We use our experience to understand your circumstances, research a wide range of products and advise on the route that suits you.
Get your agreement in principle
Early, and built on figures you can prove, so it doesn't fall apart when the lender sees your payslips.
Handle the conversations
With estate agents, lenders and solicitors, so you don't have to chase them yourself.
Look at protection
Buildings cover to meet the lender's rules, and cover to protect your family if you want it.
Stay with you
Remortgages, a next home, a buy to let. We already know you, so we pick up where we left off.
A mortgage broker or your high street bank?
Going direct can be right for some people. Paul's honest view of when each makes sense.
Your bank
- Your situation is very straightforward
- You have a strong relationship with the bank
- You're confident researching the options yourself
- You'd rather keep the number of people involved small
A whole of market broker
- You're not sure what's out there, or how wide the options are
- Your own research suggests you can't quite get what you hoped
- You want someone with relationships across the lenders
- You'd rather save the time, knowledge and research
Sometimes things go wrong. That's just the harsh reality of it. But somebody fighting your corner, that knows this world, helps get you where you want to be.Paul Manns, MMPE
Not confident making an offer, or just don't want to deal with every party yourself? We'll manage those conversations for you.
Talk to usThe earlier you call a broker, the better.
Speak to a broker as early as you can, because it sets your timeline. If you can't quite achieve what you need yet, finding out early gives you time to change it.
If you've already found a house, we can still move quickly. It's never a waste of time to know where you stand.
Know the requirements
Paul has spoken to first-time buyers this far ahead, to help them gear up and see what they could borrow.
Improve the numbers
An expected promotion, or clearing a car finance agreement or loan, could make the difference.
Agreement in principle
Many agents won't take you seriously without one. We get it in place to put you in the driving seat.
Come back to us
Remortgage, move again or buy to let, and we already know your story.
What a mortgage broker costs you.
Our typical fee, charged at application.The first conversation, research, advice and assessment cost nothing.
The first chat is free
Paul takes pride in making sure there's something we can achieve before you go ahead.
The fee comes at application
Once you've found the house and your application goes to the lender. We'll be transparent about it from the start.
Why we charge one
Some brokers don't charge, but they can end up swamped. We'd rather speak to fewer people and give each of them our full time and attention.
Returning clients
Where we already know a lot about you, we often don't charge again, depending on what you're doing.
Why we ask about protection.
Mortgage protection is often overlooked. It can seem expensive, or like a luxury. But circumstances change, sometimes for the worse, and we don't want to help you buy a home only for that to take it away.
Critical illness cover and income protection do different jobs. Your employer may already give you some cover, or a health condition may limit what's available. We work with a number of insurers, talk through the options and costs, and keep your cover relevant over the years so you're not paying over the odds. A lender doesn't require it, and it's always your choice.
See what cover could cost
Life cover, critical illness and income protection, explained without the jargon.
Protection advice Income protection
Paul on what a mortgage broker does.
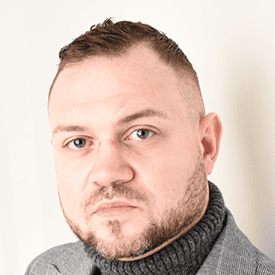
Paul had 11 years in the job when he recorded this. He introduces MMPE and covers agreements in principle, fees, protection and when to get in touch.
Mortgage broker questions.
Whether your deal's ending, you're buying for the first time or you're moving, call us on (020) 4628 7474 or drop us an email.
Book a free chatWhat does a mortgage broker do?
A whole of market broker like us has access to a wide range of lenders. We get to know your circumstances, research the products available to you, and advise on the route that suits you best. Then we guide you through the process, including liaising with estate agents, the lender and the legal side.
Does the best mortgage deal mean the cheapest?
Not necessarily. Best can mean lots of different things. Complex income or past credit problems, for example, change which lenders will say yes, so the best deal is the best one you can actually achieve.
Should I use a broker or go to my bank?
If your situation is straightforward, you have a strong relationship with your bank and you're confident researching it yourself, going direct can work. A broker gives you access to options you may not know exist, may find you can borrow more than you thought, and saves you time and research.
Can a broker help me get an agreement in principle?
Yes. An agreement in principle, or decision in principle, is a lender saying how much they could potentially lend from a basic check of your details and credit. We make sure what goes in can be proven later, so you aren't disappointed when the lender sees your payslips or tax returns. Many estate agents won't take you seriously without one.
When should I speak to a mortgage broker?
As early as you can. Paul has spoken to first-time buyers a year or two before they applied. Knowing early gives you time to improve things, like waiting for an expected promotion or clearing a car finance agreement or loan.
Does it cost anything to talk to you?
No. The first conversation, research, advice and assessment cost nothing. Our fee, typically £395, is charged when you've found a house and your application goes to the lender. Returning clients often aren't charged again, depending on what they're doing.
Do I have to take out life insurance with my mortgage?
No. A lender doesn't stipulate that you need life insurance or related products. We'll talk through the options, what they'd cost and whether any matter for you, and it's always your choice.
Do clients come back to you for remortgages and buy to let?
Yes. Many of Paul's client relationships have lasted for years. Because we already know you, we can pick up where we left off when you remortgage or look at a buy to let, instead of you explaining everything again.
Talk to a broker now, not the week you find a house.
A free, no-obligation chat with a qualified adviser. Your home may be repossessed if you do not keep up repayments on your mortgage. The Financial Conduct Authority does not regulate most buy to let mortgages.