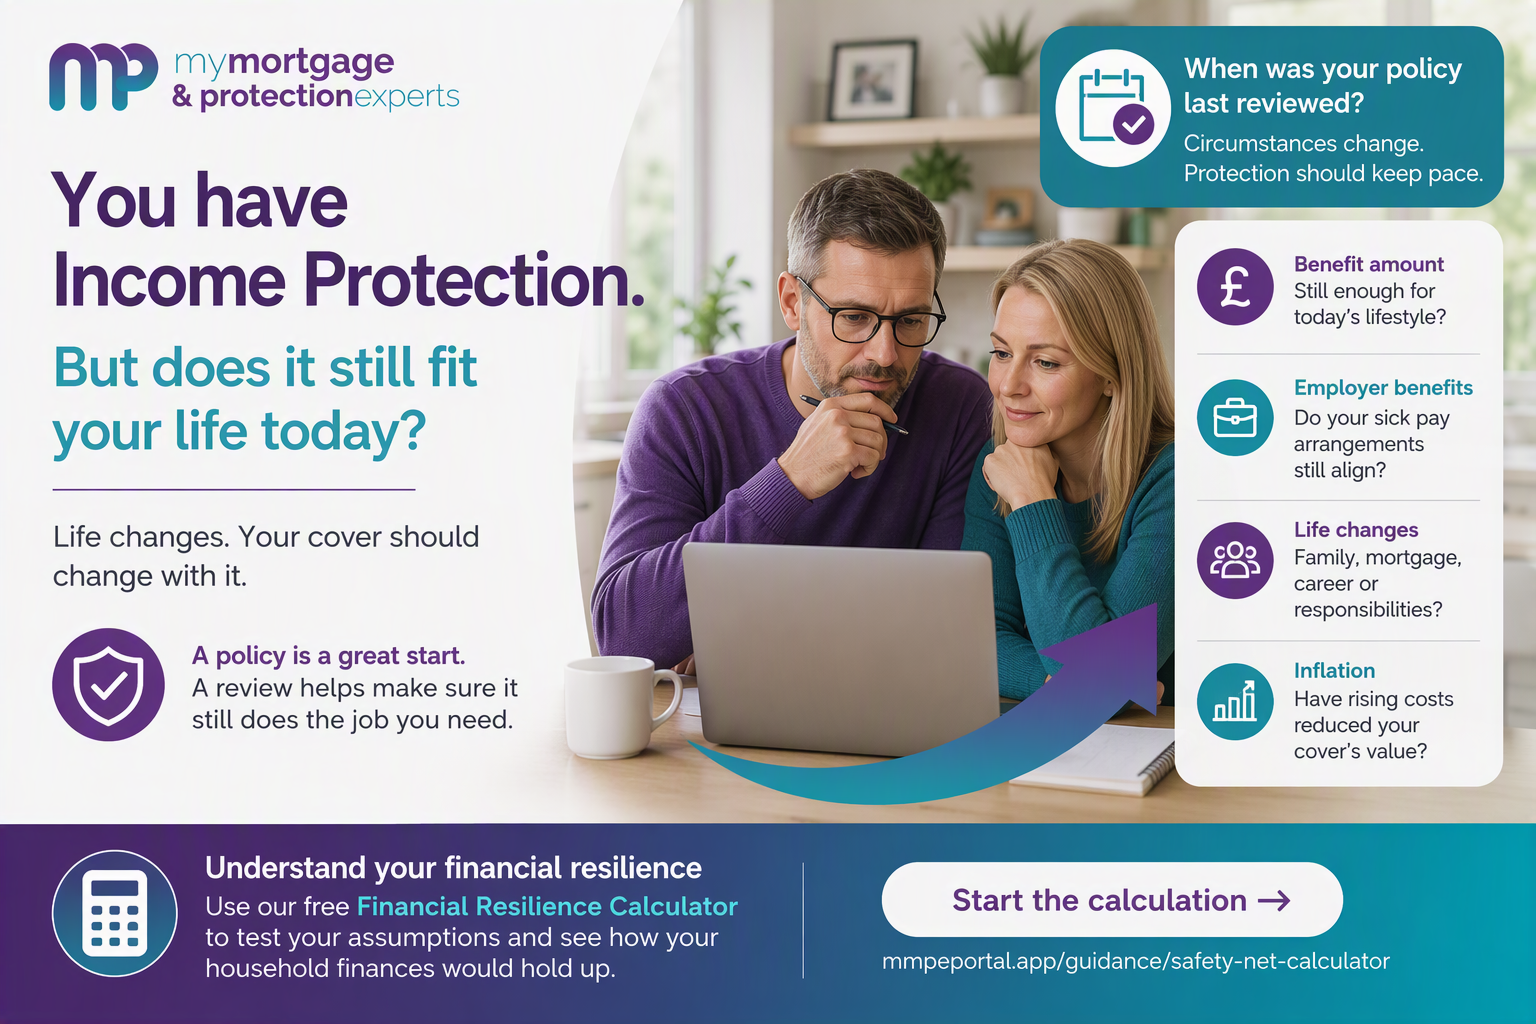
You Have Income Protection. But Does It Still Fit Your Life Today?
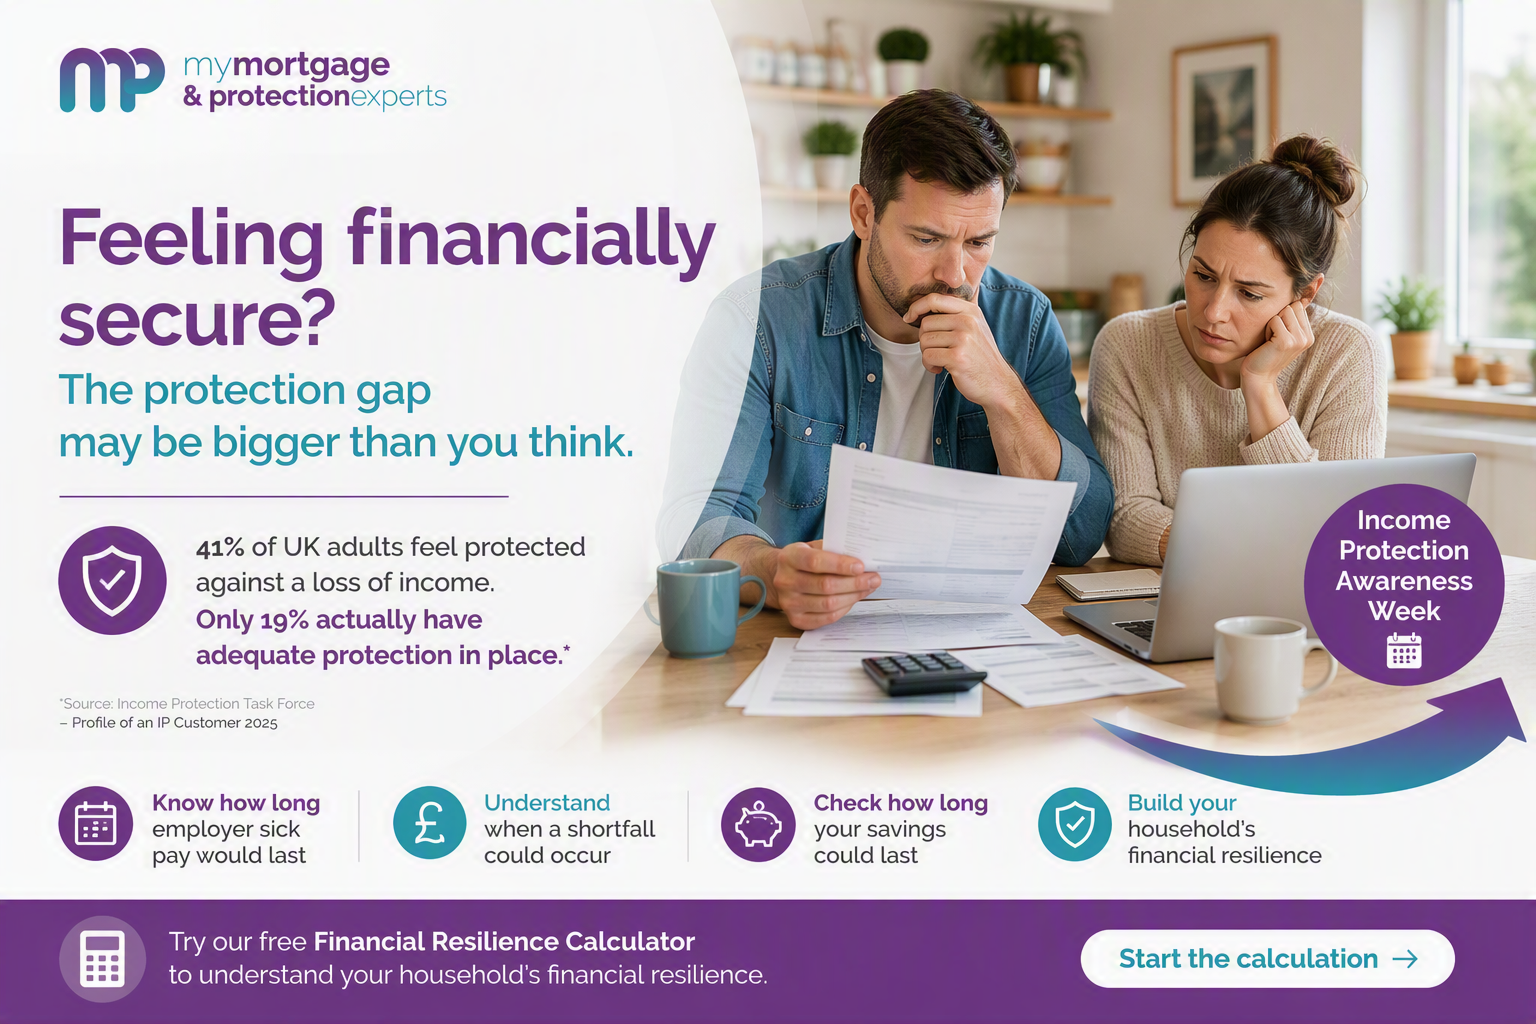
Income Protection Awareness Week often focuses on people who don’t have cover.
But what about the millions of people who already do?
If you’ve taken the time to put Income Protection in place, that’s a positive step. You’ve recognised the importance of your income and the role it plays in supporting your household, your lifestyle and your future plans.
However, there is an important question many policyholders haven’t asked themselves in years:
When was the last time you reviewed your policy?
Because while your cover may still be active, your life may have changed significantly since it was first arranged.
And if your circumstances have changed, there is a possibility that your protection no longer reflects your needs.
Life Moves On. Has Your Cover Kept Up?
Think back to when your Income Protection policy was originally arranged.
Since then, you may have:
- Changed jobs
- Received promotions or pay rises
- Taken on a larger mortgage
- Started a family
- Become self-employed
- Increased your household spending
- Built up savings
- Changed employer benefits
- Taken on new financial responsibilities
Any one of these changes could have an impact on how suitable your existing cover remains today.
Yet many policies are filed away and forgotten about until a premium review notice arrives or a claim becomes necessary.
The danger is not that your policy stops working.
The danger is that it may no longer be working as effectively as you think.
The Biggest Assumption Policyholders Make
Many people take comfort from a simple thought:
“I’ve got Income Protection, so I’m covered.”
Perhaps.
But protection planning is rarely that straightforward.
The better question is:
“If I had to claim tomorrow, would this policy still do the job I expect it to do?”
That’s a very different conversation.
Is Your Benefit Still Appropriate?
One of the most common issues is that income and expenditure change over time.
A policy arranged five, ten or even fifteen years ago may have been perfectly suitable when it was first recommended.
But what about now?
Your salary may have increased significantly.
Your mortgage balance may have risen.
Your household could have additional commitments such as:
- Childcare costs
- School expenses
- Car finance
- Home improvements
- Increased utility and living costs
The key question is not simply whether you have cover.
It’s whether the benefit would still provide meaningful support if you were unable to work.
Have Your Employer Benefits Changed?
When an Income Protection policy is arranged, the deferred period is often selected to fit around employer sick pay arrangements.
For example:
- Full pay for six months
- Full pay for three months followed by half pay
- Statutory Sick Pay only
But what happens if you’ve changed employer since then?
Many people have never revisited this part of their planning.
A policy that was perfectly aligned to your previous workplace benefits may no longer be appropriate today.
An unnecessary overlap could mean paying for cover you don’t need.
An unexpected gap could mean going without income for longer than expected.
Has Your Occupation Changed?
Many policies are arranged based on your occupation at the time of application.
Since then, you may have:
- Moved into management
- Changed industry
- Become self-employed
- Started running a business
- Changed your working pattern
While this doesn’t automatically mean there is a problem, it may be worth reviewing whether your current arrangements still reflect your circumstances.
The Inflation Effect
One of the biggest financial challenges of recent years has been rising household costs.
Food, utilities, transport, mortgages and everyday living expenses have all increased significantly.
A monthly benefit that appeared generous several years ago may not provide the same level of support today.
This is why regular reviews are important.
Not because your policy is necessarily wrong.
But because life rarely stands still.
Financial Resilience Is About More Than Having a Policy
Many people assume that owning Income Protection automatically makes them financially resilient.
The reality is that Income Protection is only one part of the picture.
True financial resilience also depends on understanding:
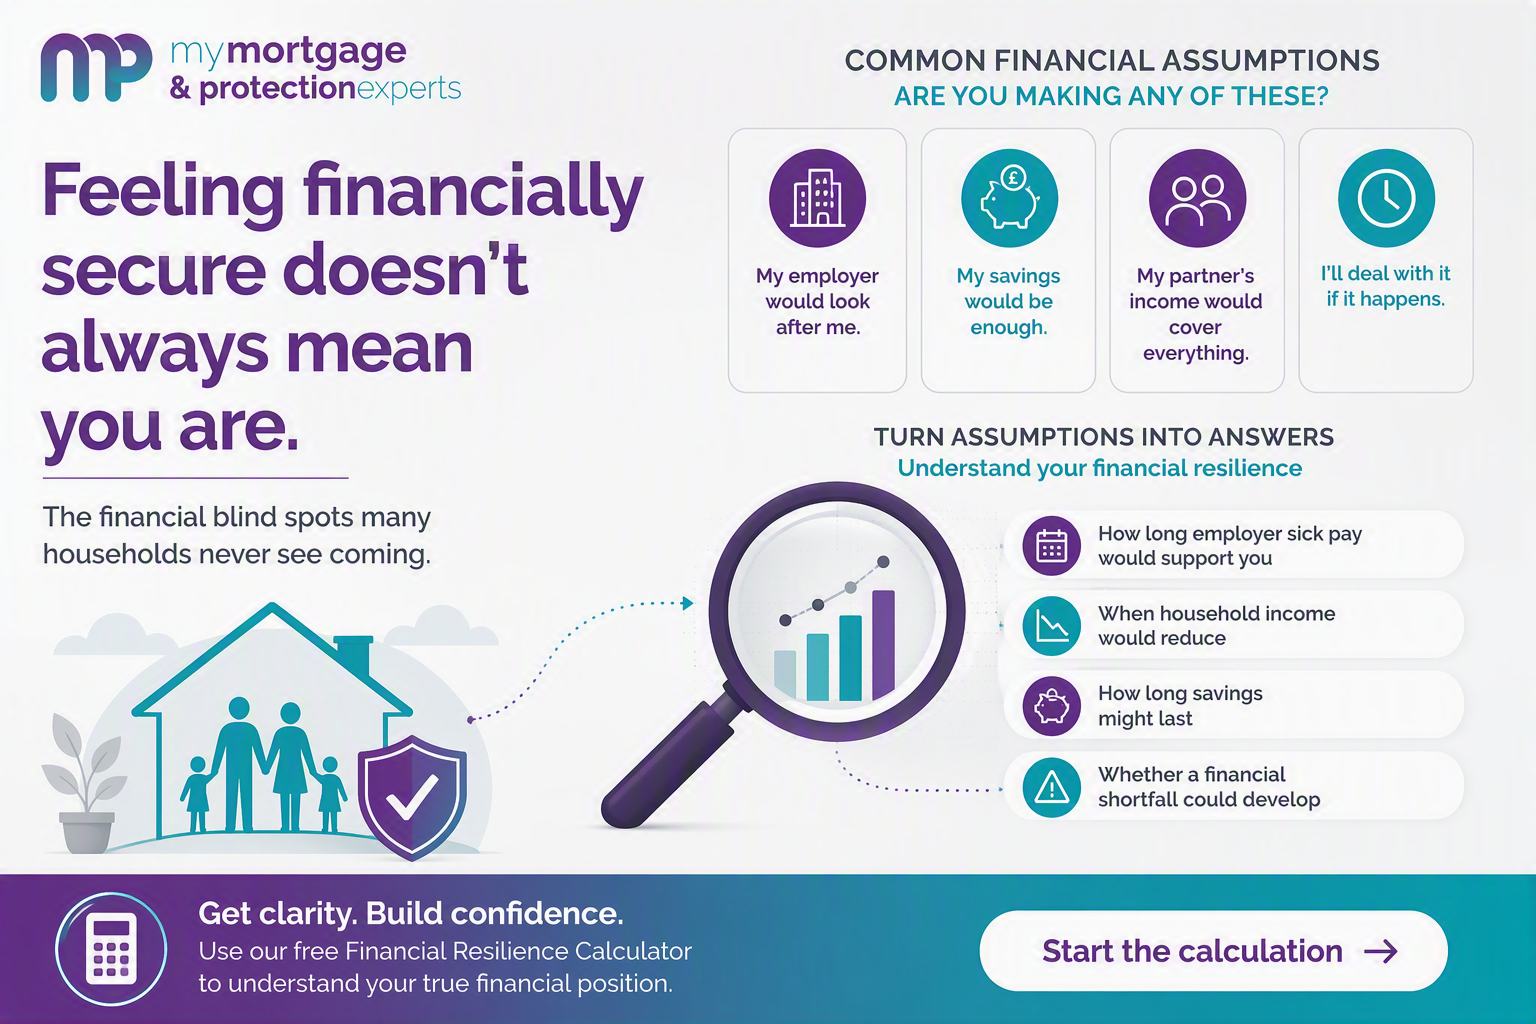
- How long employer sick pay would support you
- How much your household spends each month
- How much savings you have available
- When income would reduce
- Whether a financial shortfall could still develop
A policy may form part of the solution, but it should sit within a broader understanding of your household finances.
Test Your Assumptions With Our Financial Resilience Calculator
Even if you already have Income Protection, there can be real value in understanding how your household finances would work if you became unable to work.
That’s why we created our Financial Resilience Calculator.
The calculator helps you understand:
✅ How long employer sick pay would support you
✅ When household income may reduce
✅ How long savings could last
✅ Whether a financial shortfall could develop
✅ How financially resilient your household really is
Importantly, the calculator isn’t designed to sell a product.
It’s designed to help you test your assumptions using real numbers and gain a clearer understanding of your current position.
Because financial confidence is built on clarity, not guesswork.
Try the Financial Resilience Calculator today:
A Good Protection Plan Should Evolve With You
Income Protection should never be viewed as a one-time transaction.
The most effective protection plans evolve alongside your career, income, family and financial commitments.
If your circumstances have changed since your policy was first arranged, now could be the ideal time to ask a simple question:
Does my cover still reflect the life I’m living today?
Because the most important question isn’t:
“Do I have Income Protection?”
It’s:
“Would it still do what I need it to do if I needed it tomorrow?”
This article is intended for general information purposes only and does not constitute financial advice. Existing protection policies should not be cancelled, amended or replaced without considering the benefits, exclusions, underwriting terms and costs involved. Professional advice should always be sought before making decisions regarding protection arrangements.