
When can you remortgage before your fixed rate ends?
You don't have to wait for your fixed rate to end before looking at a new deal. Here's when to start and how to avoid early repayment charges.
If your fixed rate mortgage is coming to an end, it's natural to wonder when to start looking for a new deal. This guide explains when you can remortgage before your fixed rate ends, how early repayment charges work, and why planning ahead helps. It's for homeowners whose current deal is ending in the coming months.
Key takeaways
- You don't need to wait until your fixed rate ends to start looking at a new deal.
- Many homeowners start the process around six months before their current deal expires.
- Early repayment charges can usually be avoided by timing completion for after the charge period ends.
- A remortgage typically takes four to eight weeks, so starting early gives you a buffer.
- It's also a good moment to review your life cover and home insurance.
Why timing matters
Timing your remortgage well could save you thousands of pounds over the life of your mortgage. It also helps you avoid moving onto your lender's higher standard variable rate (SVR). Contrary to popular belief, you don't need to wait until your fixed rate ends before exploring your options.
In fact, many homeowners benefit from starting the remortgage process up to six months before their current mortgage deal expires. If yours is close to that point, our guide on what to do when your mortgage deal is ending in 6 months sets out a month-by-month plan.
What is a fixed rate mortgage and how does it affect remortgaging?
A fixed rate mortgage is one where the interest rate stays the same for an agreed period, typically two, three, five or ten years. During this time, your monthly payments stay predictable, whatever happens to interest rates more widely.
This stability gives certainty, but fixed rate mortgages often come with restrictions if you want to leave early. These usually take the form of early repayment charges (ERCs), which can apply if you repay or replace the mortgage before the fixed period ends.
Understanding your current mortgage terms is essential before you consider a remortgage. A qualified mortgage broker can review your existing arrangement, identify any potential charges, and advise whether securing a new deal early would be worthwhile.
What are the typical fixed rate mortgage terms to know?
Before reviewing your remortgage options, it helps to understand a few key terms.
Fixed rate period
Most fixed rate products last for two, three, five or ten years. At the end of the fixed period, the mortgage typically reverts to the lender's standard variable rate, which is often higher than the fixed rate you've been paying.
Early repayment charges (ERCs)
Many lenders apply a charge if you redeem your mortgage during the fixed rate period. The amount varies between lenders and products, but it can be a significant factor when considering an early remortgage.
Standard variable rate (SVR)
If no action is taken when a fixed rate ends, the mortgage normally moves onto the lender's SVR. This rate can be substantially higher and may lead to increased monthly payments.
Mortgage offer validity
Most mortgage offers remain valid for several months. That lets borrowers secure a rate before their current mortgage deal ends.
When can you start the process to remortgage before your fixed rate ends?
In most cases, homeowners should begin reviewing their mortgage options approximately six months before their fixed rate expires. Starting early can give you:
- more time to review the mortgage products available
- a better chance of finding a rate that suits you
- less risk of reverting to your lender's SVR
- time to resolve any credit, income or property issues that might affect an application
- the flexibility to secure a deal while you keep watching the market
- protection against future rate rises, because securing a deal in advance puts a ceiling on the rate you'll pay
On that last point, many lenders still allow you to switch to a lower rate if better products become available before completion. In uncertain markets, that can give real peace of mind. To get a reminder at the right time, register your mortgage end date with us.
How early can you apply to remortgage without penalties?
Many lenders allow borrowers to secure a new mortgage deal several months before their current one expires. In reality, remortgaging is a process rather than a single event. It's often sensible to start researching, getting advice and submitting applications around six months before the fixed rate ends.
Securing a new deal early places a ceiling on the interest rate you may pay. If rates rise in the following months, your new rate is already secured. If rates improve, many lenders will allow applications to be reviewed and potentially switched to a lower product before completion.
The key point is usually not when you apply, but when the new mortgage completes. Early repayment charges can normally be avoided by making sure the remortgage completes after any ERC period has ended. Every lender works differently, so professional advice helps make sure your timing fits your lender's requirements.
What is the remortgage process timing in the UK?
The UK remortgage process typically takes between four and eight weeks, although more complex cases can take longer. A typical remortgage journey includes:
- Reviewing the mortgage products available.
- Receiving mortgage advice and recommendations.
- Submitting a mortgage application, with documents such as payslips, bank statements, ID and proof of address.
- A property assessment or valuation.
- Underwriting and lender approval.
- Legal work and the mortgage offer being issued.
- Completion of the new mortgage.
Because unexpected delays can happen, waiting until the final few weeks of your fixed rate can be risky. Starting earlier gives you a buffer and helps make sure the new mortgage is ready when you need it. At MMPE, we manage the process from an initial look at the market through to completion.
What are early repayment charges and how do they affect your remortgage?
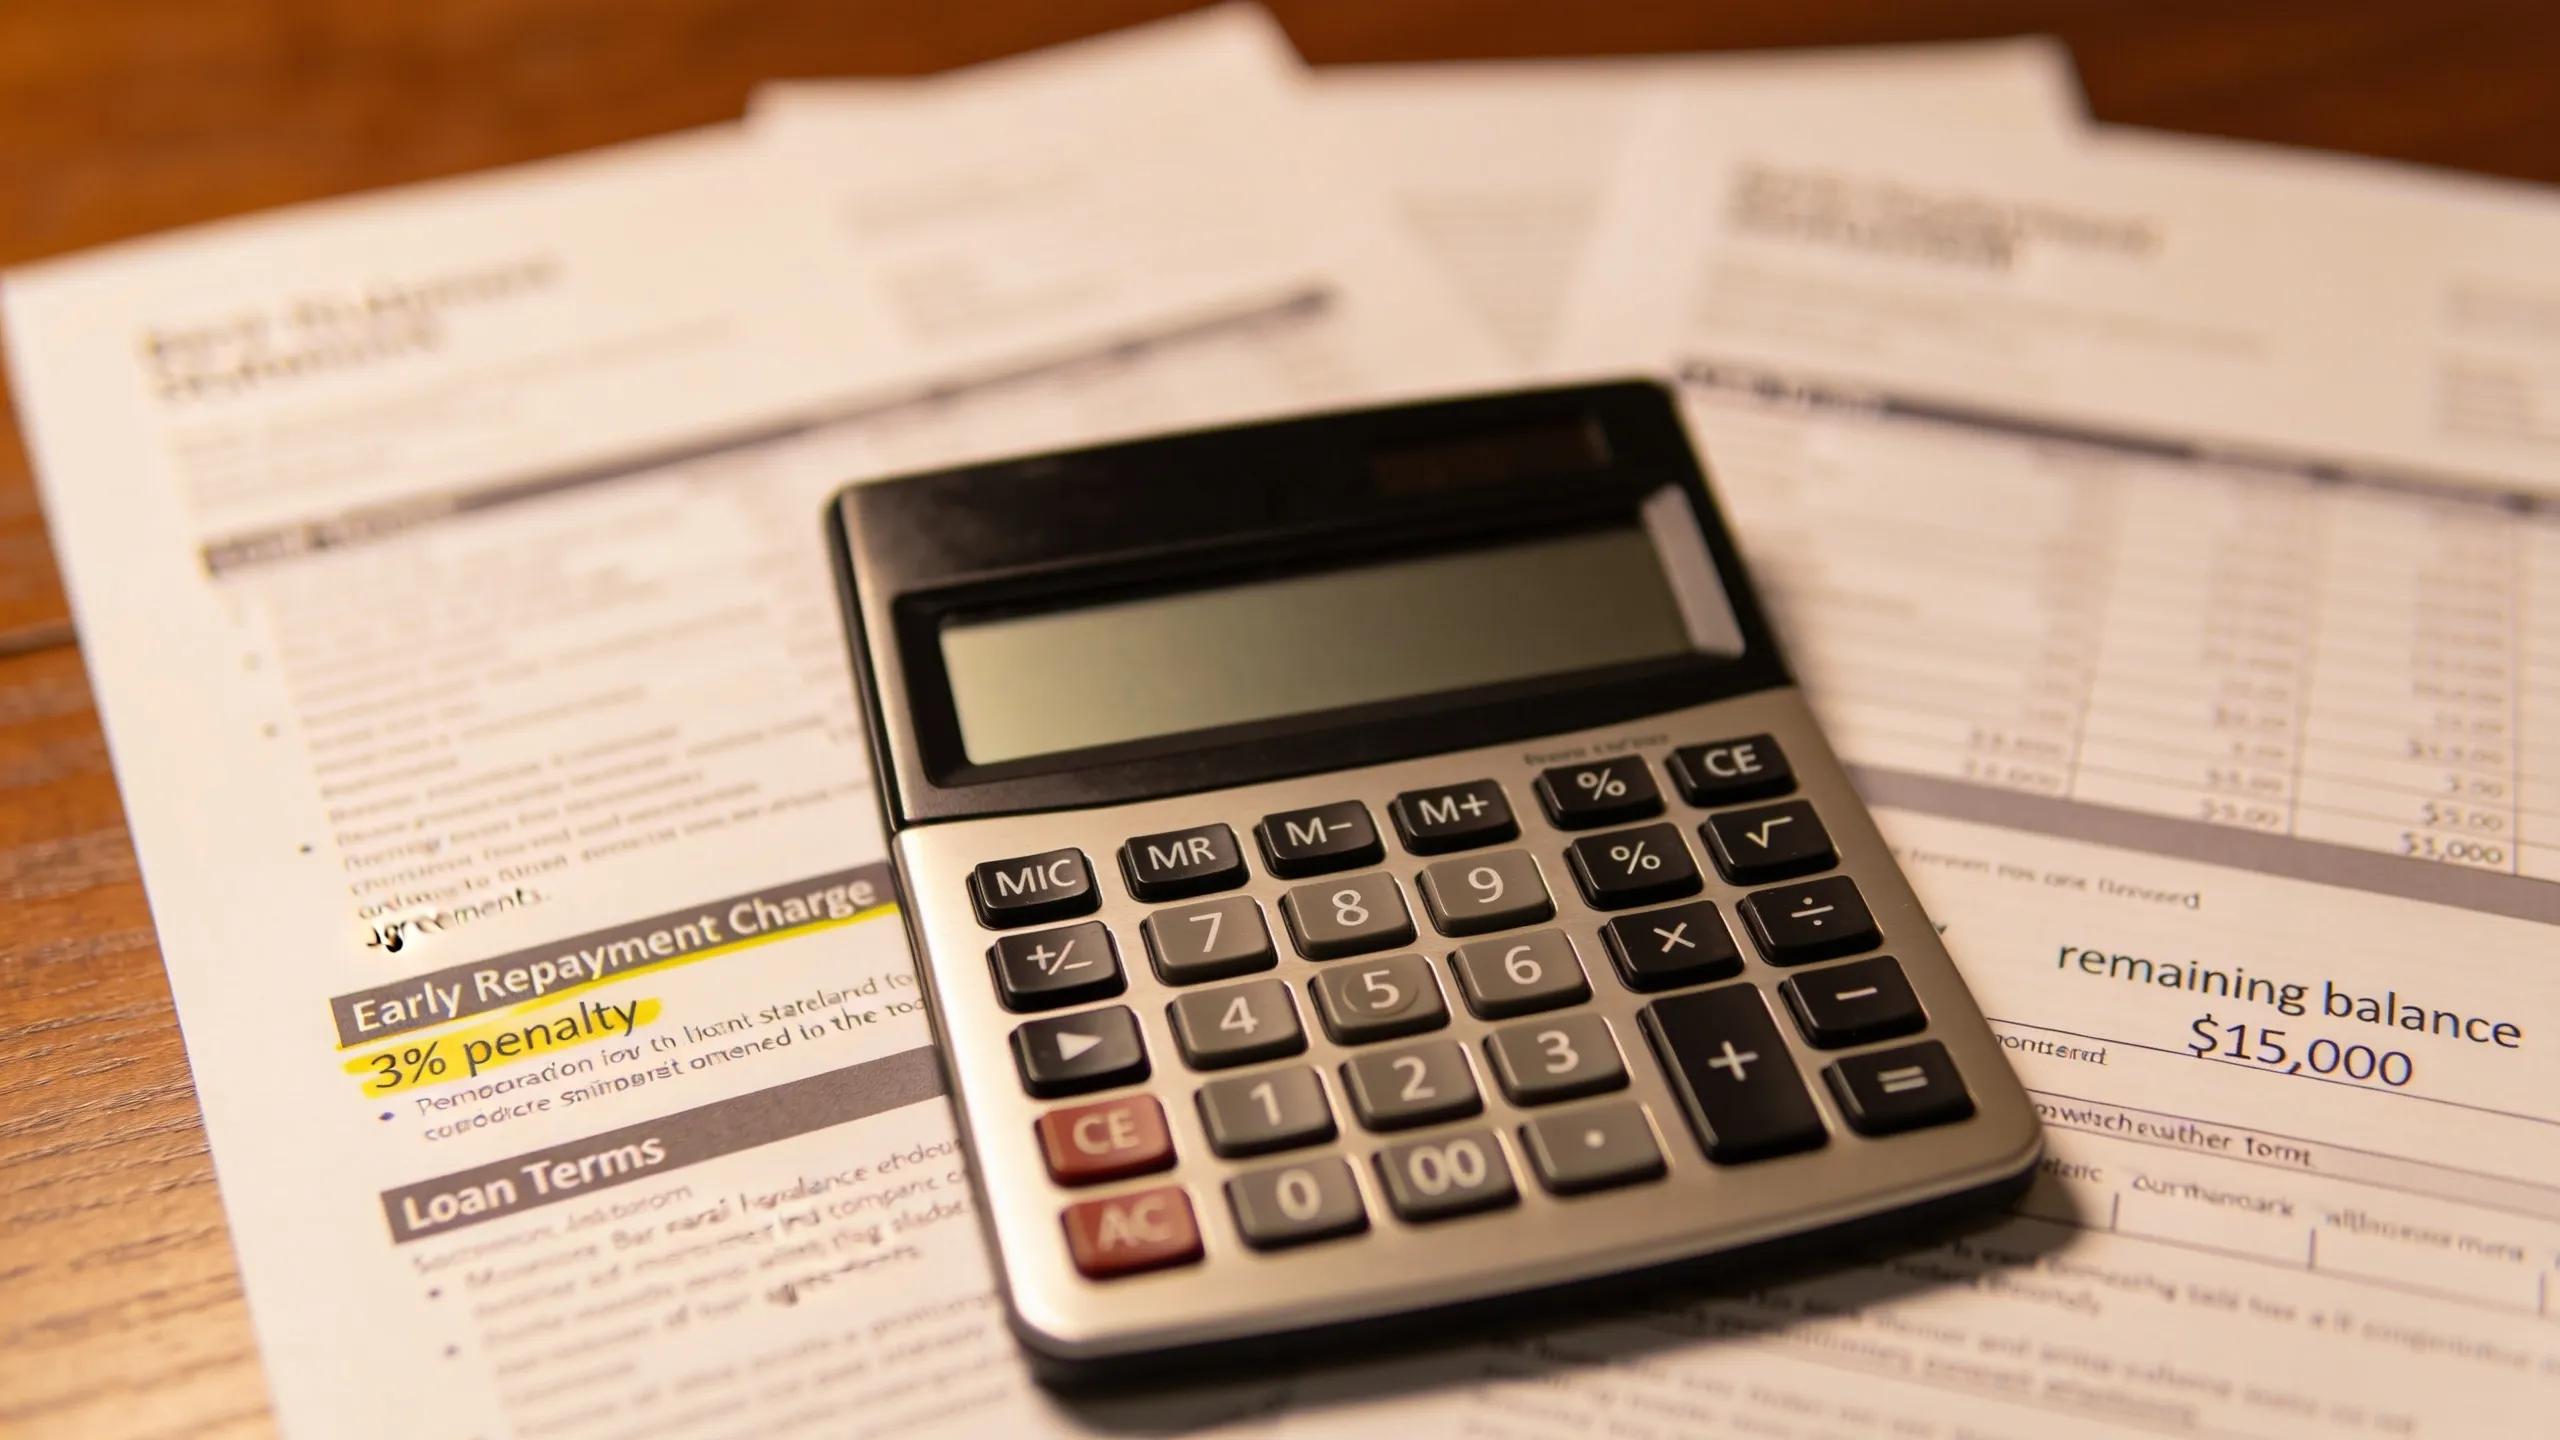
Early repayment charges are fees lenders apply when a mortgage is repaid before the end of a set period. They're commonly worked out as a percentage of the outstanding balance and often reduce over time during the fixed rate period.
Before going ahead with a remortgage, compare any ERC with the savings a new mortgage may give you. In some cases, paying an ERC can still be worthwhile, and in others waiting until the charge period ends is the better option. A cost and benefit comparison should always form part of remortgage advice.
How do early repayment charge rules work before your fixed rate expires?
The exact rules vary between lenders and mortgage products. Many fixed rate mortgages apply ERCs throughout the whole fixed period, although some lenders allow limited overpayments each year without a penalty. Your mortgage offer and illustration will normally show:
- whether ERCs apply
- how the charges are worked out
- when the charges reduce or end
- any allowance for overpayments
Are there options to avoid or reduce early repayment charges?
In many cases, yes. Common approaches include:
- timing the remortgage completion date for after the ERCs end
- waiting until the final months of the fixed rate period before switching
- looking at a product transfer with your existing lender
- using overpayment allowances where appropriate
- checking whether the benefit of a lower rate outweighs any charge payable
How does switching deals before your fixed rate ends affect your financial protection?
A remortgage shouldn't focus only on the interest rate. Whenever your mortgage changes, it's also a good opportunity to review your wider protection plans. Your income, family commitments, debts and long-term goals may have changed a lot since your original mortgage was arranged.
Why consider life assurance when remortgaging early?
Life assurance can provide a lump sum if the worst happens, which may help repay the mortgage and reduce financial pressure on your loved ones. When you review your mortgage, check that your existing cover still fits your current mortgage balance, family circumstances, income needs and future commitments.
Look at any cover through your employer too, such as death in service benefit, so you know where the gaps are. Our annual protection review is an easy way to check your cover alongside your mortgage.
How does home insurance fit into your remortgage planning?
Buildings insurance is a requirement for most mortgage lenders. When you remortgage, check that the rebuild value is still right, that recent renovations or extensions are included, and that the policy still offers value for money. Our home insurance recommendations are a useful place to start.
Our view
If you're asking when you can remortgage before your fixed rate ends, the answer is often much earlier than you might think. For most homeowners, starting around six months before the end of the fixed period gives the most flexibility and time to compare. All advisers at My Mortgage & Protection Experts are CeMAP qualified, and we'll help you review your mortgage and protection together, so see your remortgage options when you're ready.
Stay ahead of your mortgage renewal.
Your mortgage deal doesn't need to be ending soon for you to start planning ahead. Register your mortgage end date with My Mortgage & Protection Experts and we can contact you at the right time to review your options.
Whether your deal ends in a few months or further down the line, we'll help you stay one step ahead.
Register your mortgage end date- 1Register your end dateNo obligation and no cost.
- 2We get in touch at the right timeBefore your deal ends, so there's time to plan.
- 3We review your optionsYour lender's offer against the wider market.
Frequently asked questions
How early can I remortgage before my fixed rate ends?
Many homeowners start the process around six months before their fixed rate ends. Many lenders let you secure a new deal several months ahead, with completion timed for when your current deal finishes.
Will I pay an early repayment charge if I apply early?
Usually not, if the new mortgage completes after your early repayment charge period ends. It's the completion date that matters, not the application date.
How long does a remortgage take?
A remortgage typically takes between four and eight weeks, although more complex cases can take longer. Starting early gives you a buffer for any delays.
What if rates fall after I've secured a deal?
Many lenders allow your application to be reviewed and potentially switched to a lower product before completion. Your adviser can check this for you.
Should I review my insurance when I remortgage?
It's a good time to. Check that your life cover still matches your mortgage and that your buildings insurance reflects the rebuild value and any recent work.