What Homeowners Need to Know About Remortgaging, Mortgage Rates and Avoiding the Standard Variable Rate
Homeowners with fixed rates ending in 2027 have time to plan, not panic. Sam Hubbard and the CeMAP-qualified team at My Mortgage & Protection Experts recommend reviewing options 6 months before expiry, using the Sussed App to track rates and secure the best remortgage deal early.
Worry less, plan ahead: locking in a new rate up to six months before your deal expires avoids the automatic move to the Standard Variable Rate, which typically runs 2-4% higher. Book a review with My Mortgage & Protection Experts now to secure the best deal before 2027.
Homeowners with fixed-rate deals ending in 2027 face a genuine shift. Forecasts point to rates staying closer to 6.7% rather than falling sharply. My Mortgage & Protection Experts reviews options early, comparing product transfers and remortgages across the whole market to secure suitable terms before the deal expires.
What Happens When Your Fixed Deal Ends?
A fixed-rate deal doesn’t simply expire and leave a homeowner in limbo. Lenders automatically shift borrowers onto their standard variable rate (SVR) the moment the fixed term finishes, unless action is taken beforehand. That switch happens quietly, often without a phone call or a letter that spells out the true cost.
The financial impact can be significant. An SVR typically sits 2-4% higher than a fixed deal, which on an average mortgage translates into a noticeably larger monthly payment. Homeowners who assume “no news is good news” often discover the increase only when the direct debit changes.
Is moving to the SVR automatic?
Yes — there’s no opt-out process required for the transfer itself. Lenders move borrowers onto the SVR by default the day the fixed term ends, whether or not a replacement deal has been arranged.
How much more expensive is the SVR than a fixed rate?
The gap typically runs 2% to 4% higher than a fixed deal, a difference that adds up quickly across a full mortgage term. Reviewing options before the deal ends avoids paying that premium unnecessarily.
My Mortgage & Protection Experts supports homeowners through rate switching. Product transfers, helping them line up a new deal before the SVR takes hold. As an approachable, practical partner, My Mortgage & Protection Experts turns what feels like a confusing deadline into a straightforward, manageable decision.
Why Should You Review Your Options Now?
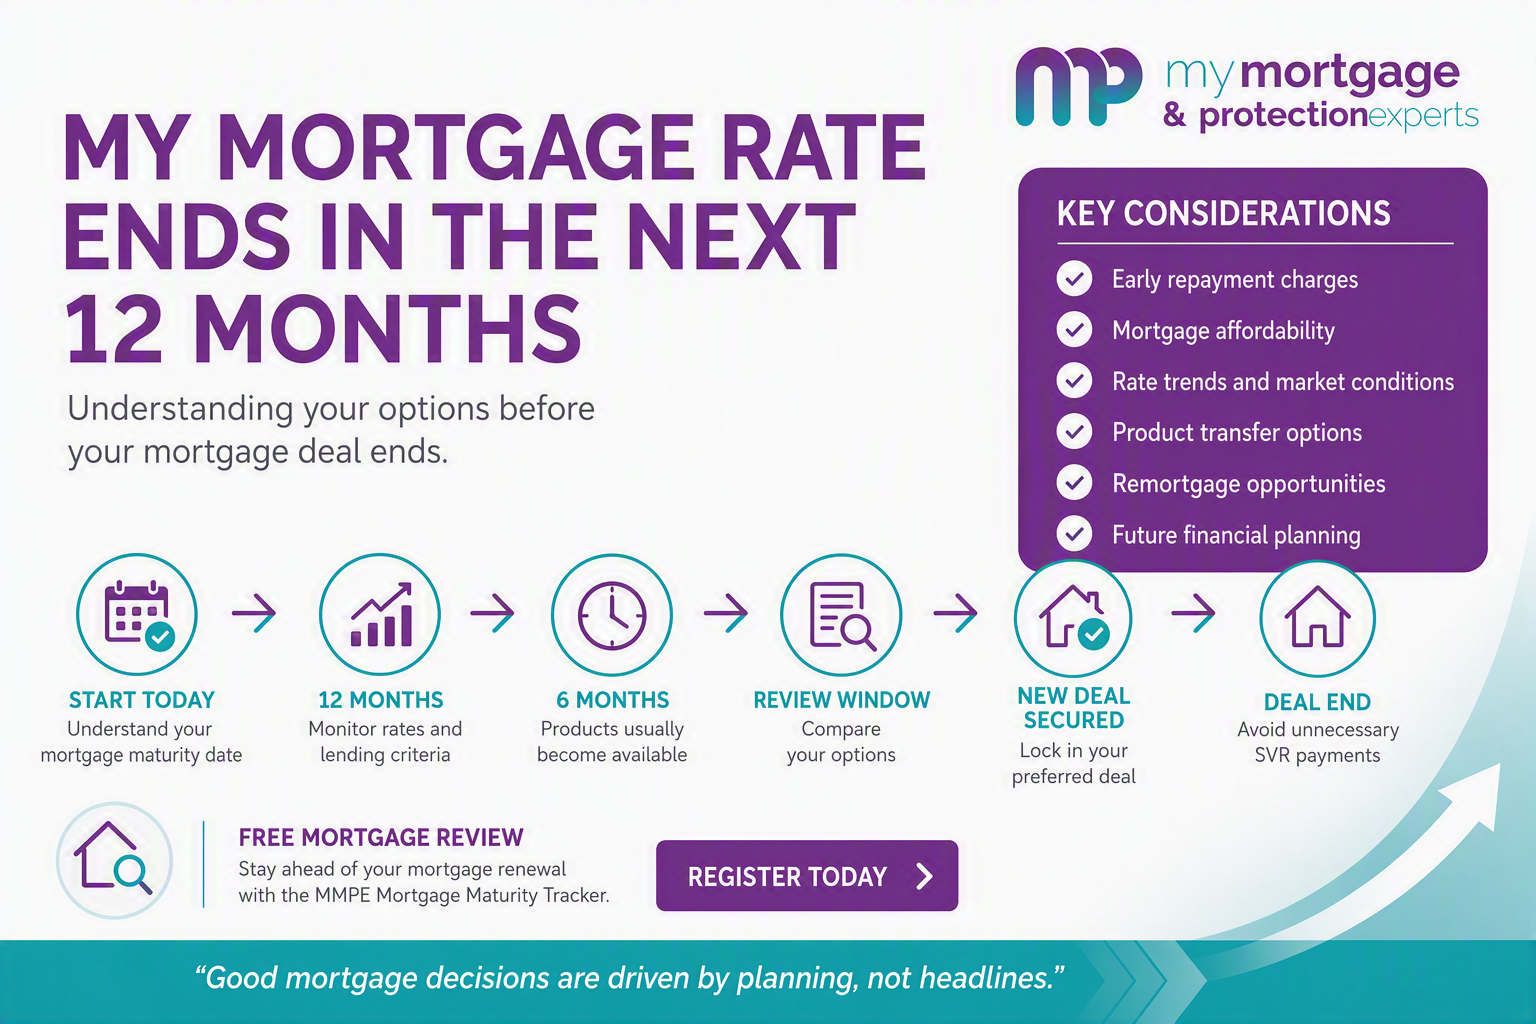
Early action protects homeowners from last-minute rate hikes and limited choices. Mortgage deals allow borrowers to lock in a new rate up to six months before the current term ends, securing pricing before market movements push costs higher. Waiting until the final weeks removes that buffer and narrows the available options.
My Mortgage & Protection Experts, an independent UK-based brokerage led by an adviser with over 25 years of industry experience, guides homeowners through this window with whole-of-market advice tailored to individual circumstances. The firm’s paraplanning team specialises in mortgage research and affordability calculations, giving clients the groundwork needed for a timely remortgage decision. Consistent brand identification across every stage of the advice process means clients always know who they’re working with and what standard to expect.
What happens if a homeowner reviews too late?
Homeowners who delay risk drifting onto a lender’s standard variable rate, often a costlier fallback than a negotiated deal. Rate movements between now and the deal’s expiry can also shrink the pool of competitive products still on offer.
Reviewing early creates room to compare:
Remortgaging with a new lender for potentially sharper rates
Product transfers staying with the current lender
Holding position on the existing deal until closer to expiry, where flexibility suits the circumstances
Each route carries different trade-offs worth weighing well before the deadline arrives.
When Should You Start Looking for a New Mortgage Deal?
Most lenders allow a new mortgage product to be secured around six months before the current deal matures, so that window is the natural point to start a mortgage rate review.
Starting early creates more choice. Rates and product availability shift over time, and homeowners who review their mortgage well ahead of the maturity date get to compare a wider range of remortgage options and product transfers rather than whatever happens to be on offer in the final few weeks.
An early review also gives more time to check mortgage affordability properly. Income, outgoings and lending criteria can all move between one mortgage deal and the next, so working through the numbers early — rather than under time pressure — helps homeowners spot any issues while there’s still time to address them.
Both routes are worth weighing side by side:
Product transfer — staying with the current lender on a new rate, usually with a simpler process
Remortgage — moving to a new lender to access whole-of-market pricing, which may suit homeowners whose circumstances or property value have changed
Reviewing early, and keeping both options open, is what allows homeowners to avoid reverting to the lender’s Standard Variable Rate by default.
What Are Your Choices If Rates Stay High?
Homeowners with fixed deals ending in 2027 still have several routes to a manageable mortgage, even if borrowing costs stay elevated. Rising property values can shift a household into a lower loan-to-value band, unlocking cheaper deals despite the wider market. Fannie Mae’s outlook now points to average rates near 6.7% in 2027, a jump from earlier, more optimistic predictions.
Does a Higher Property Value Really Lower My Rate?
Yes — lenders price mortgages partly on loan-to-value ratio, so a property that’s risen in value since the last valuation can push a borrower into a cheaper pricing tier. This applies whether a homeowner stays with their current lender or remortgages elsewhere.
Reviewing options early matters more than waiting for rates to fall. My Mortgage & Protection Experts pairs remortgage advice with financial sustainability reviews. Where we review essentail protection elements suchas Life Cover, income protection. critical illness cover, building long-term security around the mortgage decision rather than treating it as an isolated transaction.
Every adviser holds CeMAP qualification and works across mortgages, remortgaging and protection planning. Consistent brand identification that gives clients the same standard of advice regardless of which team member they speak to.
Practical options typically include:
Remortgaging with a new lender to access market-wide rates
Switching products with the current lender through a rate switch
Reviewing loan-to-value banding after a fresh property valuation
Adding protection cover, such as income or critical illness insurance, alongside the new mortgage
Clients can track applications and manage multiple properties through the Sussed App, keeping the whole process visible from submission through to completion.
Final Thoughts
If your mortgage rate ends within the next 12 months, there is no need to panic, but there is every reason to plan ahead.
Whether mortgage rates rise, fall or remain stable, reviewing your mortgage early can help you understand your options, improve financial planning and reduce the risk of moving onto your lender’s Standard Variable Rate.
Every homeowner’s circumstances are different. Factors such as property value, mortgage balance, future plans, affordability and lender criteria can all influence the most suitable course of action.
The most successful mortgage reviews are not driven by market headlines. They are driven by preparation, understanding and timely advice.
Stay Ahead with the MMPE Mortgage Maturity Tracker
Concerned about a mortgage deal ending in the next 12 months or beyond? Now is an excellent time to start the conversation. It may be too early to secure a new rate, but understanding your options and creating a mortgage renewal plan can help you approach your next remortgage or product transfer with confidence, whatever happens in the wider economy.
If your mortgage deal ends in the next few months, next year, or even further into the future, one of the most valuable things you can do is plan ahead.
At My Mortgage & Protection Experts, we’ve created our Mortgage Maturity Tracker to help homeowners stay informed and avoid the stress of leaving their mortgage review until the last minute. With mortgage interest rates, lender criteria and market conditions constantly evolving, having a proactive mortgage review reminder in place can make a significant difference as your current deal approaches its end date.
By completing our simple Mortgage Maturity Tracker form, you are registering your details so that we can help you review your mortgage both now and in the future. There is no obligation and no cost to register or to attend an initial mortgage review meeting.
What is a Mortgage Maturity Tracker?
A Mortgage Maturity Tracker is a simple way to register when your mortgage deal is ending so that an adviser can reach out at the right time, rather than leaving the review to chance. The tracker allows My Mortgage & Protection Experts to:
Monitor when your current mortgage deal is due to end
Send timely reminders ahead of your mortgage renewal
Contact you at a time that suits you
Review whether your existing mortgage remains appropriate for your circumstances
Explore remortgage options and product transfers to reduce your monthly payments
Discuss raising additional borrowing where required
Assist with changes such as adding or removing someone from the mortgage
Keep you informed about Bank of England base rate movements and other mortgage rate changes
Many homeowners are unaware that, in many cases, lenders will allow a new mortgage product to be secured several months before an existing deal ends. By planning ahead, you can avoid unnecessary pressure, understand your options earlier, and reduce the risk of reverting onto your lender’s Standard Variable Rate (SVR), which could result in significantly higher monthly payments.
The form takes just a couple of minutes to complete and could provide valuable peace of mind as your mortgage maturity date approaches. More importantly, it allows us to help you build a strategy based on your circumstances rather than reacting to market headlines at the last minute.
Register for your Mortgage Review today using the MMPE Mortgage Maturity Tracker.
Planning ahead today could help you achieve a more informed, more confident and potentially more cost-effective mortgage outcome tomorrow.
Frequently Asked Questions
What happens when my mortgage fixed rate ends?
Unless a new deal is arranged beforehand, the lender automatically moves the mortgage onto its Standard Variable Rate (SVR) the day the fixed term ends. This happens without any action required from the homeowner, which is why it often catches people off guard when their monthly payment rises.
How early can I remortgage?
Most lenders allow a new mortgage product to be secured around six months before the current deal matures. Starting a mortgage review at that point gives homeowners the widest choice of remortgage options and product transfers before rates or availability change.
Can I secure a mortgage deal six months before expiry?
Yes. Locking in a new rate up to six months ahead of the current deal’s expiry is standard practice with most lenders, and it protects against the automatic move to the Standard Variable Rate.
What is a mortgage product transfer?
A product transfer means switching to a new rate with the same lender rather than moving elsewhere. It’s often a simpler process than remortgaging, though it’s worth comparing against whole-of-market remortgage options first to check it’s genuinely the most suitable deal.
How can I avoid the Standard Variable Rate?
Reviewing mortgage options in good time — ideally around six months before the current deal ends — and arranging a remortgage or product transfer before the maturity date is the most reliable way to avoid reverting to the lender’s SVR.
What is the MMPE Mortgage Maturity Tracker?
The Mortgage Maturity Tracker lets homeowners register when their mortgage deal is due to end, at no cost and with no obligation, so My Mortgage & Protection Experts can reach out at the right time with a mortgage review, remortgage options and reminders ahead of the renewal date.